
Jamie Dimon has been warning since March that “the American Dream is alive, but it’s slipping out of reach for too many people—and for future generations.”
Six months on, JPMorgan Chase has identified a concrete, dollar-quantified driver of that decline: millions of aging small-business owners approaching retirement with little or no plan for passing their businesses on—creating a growing, hard-to-ignore succession problem.
In a report titled “Powering 10 Million Small Businesses,” set for release Monday, Chase surveyed 1,000 business owners and found that while 70% were in the early stages of succession planning, only 8% said they had reached an advanced stage. The bank frames that gap against an expected wave of transitions: roughly 12 million businesses, representing nearly $10 trillion in assets, are projected to change hands over the next decade. The report also warns the transition is particularly acute in industries the bank deems critical to national security, where more than half of firms have an owner age 55 or older.
A retirement wave that refuses to retire
The concern is not simply that baby boomers own a disproportionate share of U.S. small businesses; it is that many are preparing to exit in a state of near paralysis.
McKinsey’s Institute for Economic Mobility, in a February report on the “Great Ownership Transfer,” estimated that 6% to 13% of small-business closures over the coming decade could be avoided if owners planned better—closures driven not by failing enterprises but by owners who ran out of runway before finding buyers or successors. A 2025 Gallup survey found 27% of employer firms with owners 55 or older were either unsure of their long-term plan or intended to close the business outright rather than sell or transfer it. U.S. Bank’s 2025 small-business survey reported that while most owners said they became owners to build something they could pass on, a majority lacked a formal plan and described the process of figuring it out as overwhelming.
That paralysis appears at larger corporate levels as well. A recent analysis of S&P 500 companies found that at more than one-third of firms sampled, the CEO and CFO—the top two seats—were both in the retirement window at the same time, with no clear succession plan disclosed. The dysfunction, the analysis suggests, stretches from Main Street to the C-suite.
Estimates for the scale of the problem vary. Project Equity places the number of baby boomer–owned businesses expected to transition at 2.3 million, putting one in six U.S. jobs at risk; other analyses range as high as 3 million businesses, and some counts project as many as 6 million transitions by 2035. Across those estimates, the conclusion is the same: boomers are not adequately preparing the business landscape for the next generation.
The Fillmore, twice over
Nicole Williams told JPMorgan she grew up on family stories about San Francisco’s Fillmore district when it was known as the “Harlem of the West”—a stretch once rich with Black-owned businesses, music, and community before redevelopment scattered much of it and swallowed a generation of ownership with no mechanism to pass it forward.
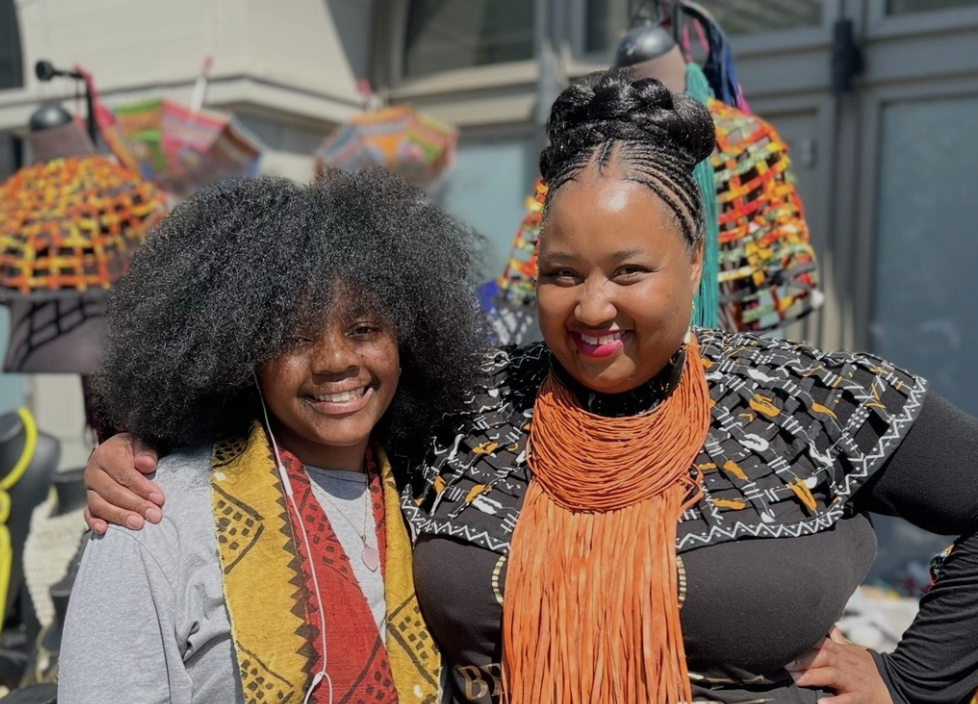
That history shaped Williams’ approach when her boutique Belle Noire began to grow. Rather than grow alone, she recruited five other Black women entrepreneurs—Vickie Brown of Ice Body Skincare, Layshaunese Fuqua of Beauty and Brains Tees, Rashida Taylor of Stash Candle Co., Tshara Ball of LB House of Beauty, and Melissa Robinson of MellRose—to open the Cowrie Collective, a shared retail space inside San Francisco’s Palace Hotel.
“We didn’t open Cowrie Collective to sell more products,” Williams says. “We opened it to make downtown feel connected again—six businesses, one vision, and a place where every purchase carries meaning.”
Williams and her partners benefited from public‑private support: SF New Deal’s “Vacant to Vibrant” program, backed by JPMorgan and the City of San Francisco, converted an empty storefront into their permanent site, helping with permitting, accessibility compliance, and the leap from pop‑up to long‑term lease. Ongoing coaching through Chase’s “Coaching for Impact” program and day‑to‑day banking support are now helping the Collective build its financial foundation. Their transition—from six solo operators to one shared enterprise—succeeded by design, the same early stage where most of Chase’s surveyed owners become stuck.
Why JPMorgan is telling this story now
JPMorgan Chase highlights Williams’ experience because most small businesses do not end up with such planned outcomes.
By putting dollar figures on the succession gap, the bank gives Dimon’s “slipping away” warning an actuarial edge: it becomes a dated, quantifiable wave rather than an abstract concern. The report also creates a policy platform for the bank to lobby on: it supports the American Ownership and Resilience Act, the Small Business Succession Planning Act, and the Retire Through Ownership Act, and urges the SBA to develop a national succession toolkit. The report links directly to money the bank pledged in its March launch of the American Dream Initiative—$80 billion in small‑business lending over 10 years—along with transition advisory services and $11.5 million in philanthropic funding for ownership transitions announced in 2025.
For every Cowrie Collective success story, many more small businesses fit the surveys’ profile: a solo founder or a handful of partners aging toward retirement with no transition plan, for whom the default outcome is shutdown rather than sale or transfer.
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.
This story was originally featured on Fortune.com.
Source: fortune.com